
Use cases
4. Statistical arbitrage
Trade spreads that are statistically bound to revert: cointegration, z-scores, and beta-neutral sizing.
Stat-arb is the quant end of pair trading: trade spreads that are cointegrated, statistically bound to revert to a mean even when they wander. The edge isn't a story; it's the math of mean-reversion.
The workflow
- Screen for pairs with high correlation and confirmed cointegration.
- Wait for the rolling z-score to stretch past your threshold (|z| ≈ 2 is typical entry territory).
- Size the legs with the hedge ratio so the position is beta-neutral.
- Exit: close as the z-score returns toward zero.
The tools on Orchard
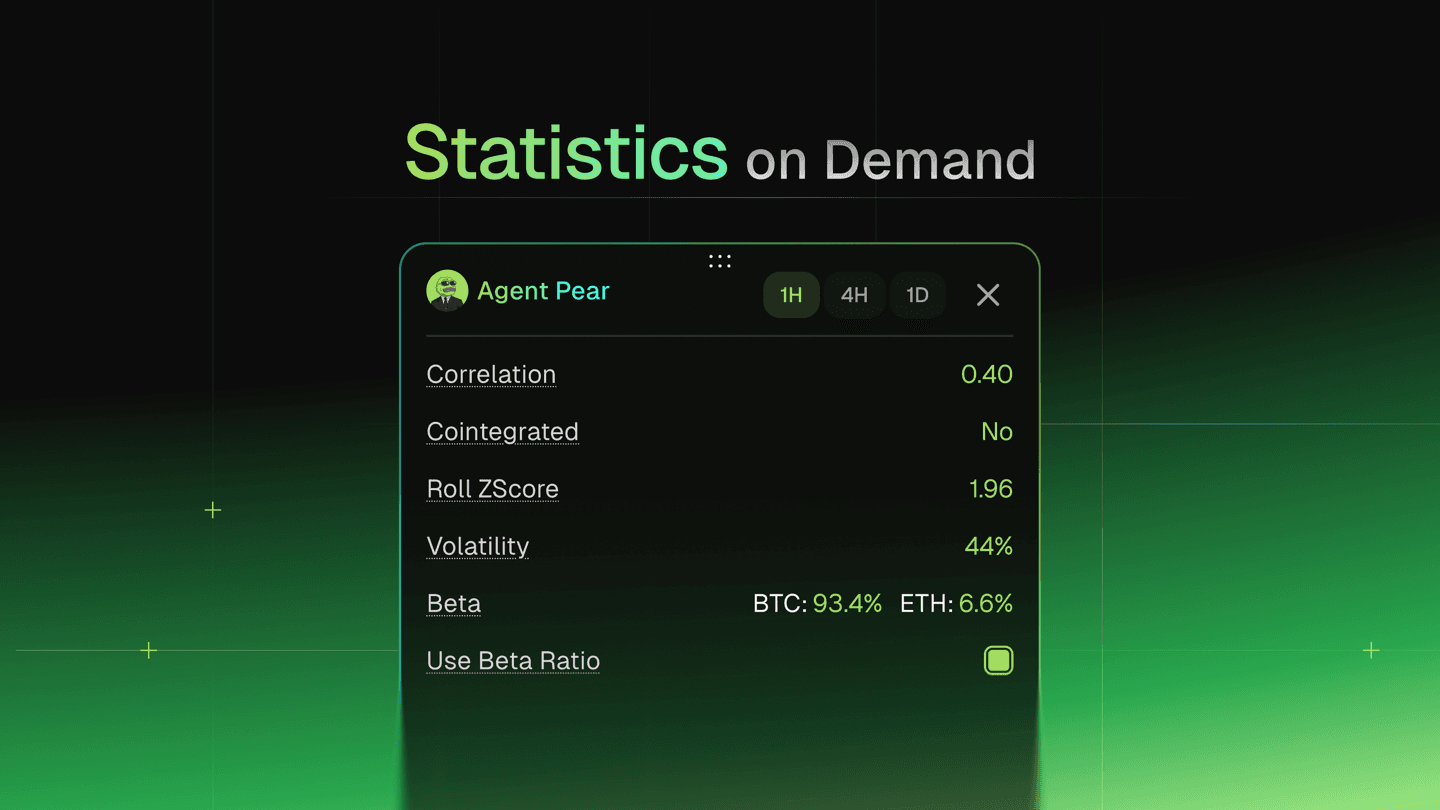
- Agent Stats panel: correlation, cointegration (Yes/No), rolling z-score, hedge ratio, and volatility for any pair, per 1H/4H/1D window.
- Agent Pear Signals: the same screen run hourly for you: candidates and active signals with live and historical performance you can open straight into a ticket (Agent Pear Signals).
- Auto-Rebalance (Beta mode): holds the position at the hedge ratio implied by the live beta feed while you wait for the spread to come home.
Statistics are recomputed hourly on a closed-candle cadence. A pair's legs partially hedge each other, but if the relationship breaks (|z| beyond ≈ 4 is a warning), both legs can move against the same collateral. See Margin & liquidations.
Related: Agent Pear Statistics · Agent Pear Signals · Auto-Rebalance